
Truck Accident Lawyer · Georgia
Hurt in a Georgia Truck Wreck With No Health Insurance? Start Here.
T. Madden & Associates, P.C. has practiced in Georgia since 1999. Learn how to handle medical bills after a truck crash, then talk with Terance Madden in a free, confidential consultation.
About T. Madden & Associates, P.C.
Since 1999
Representing injured people in Georgia
5 Offices
Jonesboro, Atlanta, Decatur, Macon and Augusta
Free
First consultation, confidential and with no obligation
24/7
Call us any time
By Terance Madden · Published October 14, 2026
If you got in a wreck and don’t have health insurance, what do I do first? Get medical care right away, keep every record, and check your own auto policy before you pay anything out of pocket. Those steps open several money paths after a Georgia truck crash.
This page explains those paths in plain terms. It covers medical bills, your own coverage, the truck company’s insurance and the dates that matter. It is general information, not advice about your specific case.
First Steps After a Truck Wreck When You Have No Health Insurance
The first step is a medical evaluation the same day, even if you feel mostly sore. Some injuries don’t show their full effects right away. A same-day exam also creates a record of how you were hurt and when.
Tell every provider your injury came from a truck crash. Say it at check-in, on the forms and to the nurse. Keep every bill, referral slip and discharge paper, even the ones that look routine.
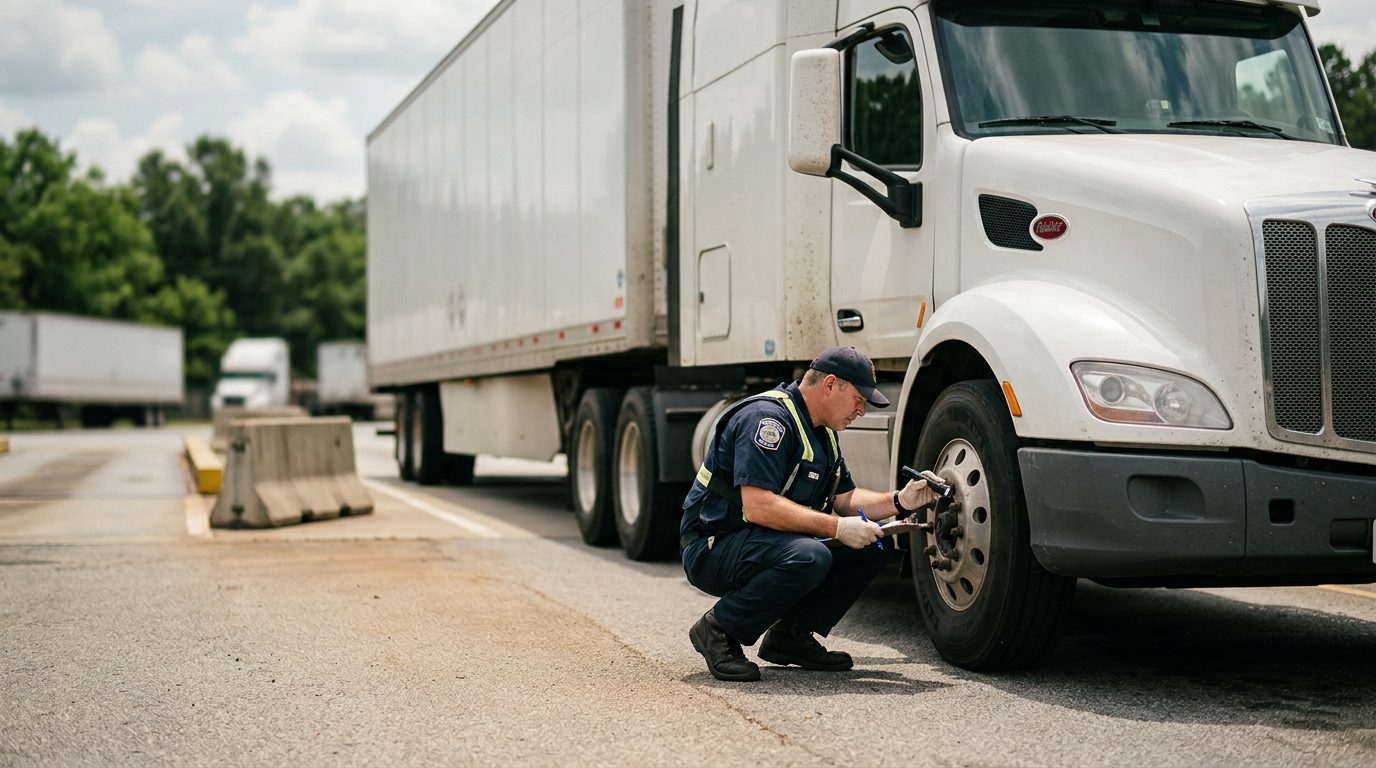
If you can do it safely, write down the truck company’s name, any DOT number on the truck, the trailer number and the driver’s name. Take photos of the truck, the scene and your injuries. Do this before details fade.
Most people asking this question worry about money first. How do I pay for this now? Don’t skip care to save money. Treatment comes first, and there are workable steps for bills while a claim is still open.
If a truck crash left you with medical bills and no health insurance, you don't have to sort it out alone; our team can talk it through with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Can Health Insurance Refuse to Cover a Crash Injury?
Sometimes a health plan may deny or delay payment when another party might be responsible for the injury. Some plans later ask to be repaid from a settlement. Whether that applies depends on your plan’s written terms, not on a general rule.
Don’t assume your plan will pay, and don’t assume it won’t. Ask the plan in writing how it handles injuries caused by someone else. Ask what it needs from you and by when.
Keep every explanation-of-benefits letter, denial notice and note from each phone call. Write down the date, the time and the name of each person you spoke with. These papers show what was billed, what was paid and why.
A written answer from the plan is worth more than a phone answer you can’t prove. Read any reimbursement form carefully before you sign it.
Check Your Own Policy for Uninsured Motorist and Medical Payments Coverage
Your own auto policy may be the first place to look for help. Two coverages matter most: uninsured motorist (UM) coverage and medical payments (MedPay) coverage.
Under O.C.G.A. § 33-7-11, Georgia auto policies generally include uninsured motorist coverage unless the named insured rejects it in writing, and an insured may also select a lower UM limit in writing, but not below the minimum the statute sets. Check your declarations page to confirm which coverage and limits you have. The coverage pays, up to its limits, the damages the insured is legally entitled to recover from an uninsured owner or operator. The statute also counts a vehicle as uninsured when its liability insurer has legally denied coverage. A denial doesn’t end the question.
MedPay works differently. If your policy includes it, it can help pay medical bills from the crash. Your declarations page lists each coverage you bought and its limit.
Before you call your insurer, gather your policy number and declarations page. Ask whether UM and MedPay apply to this crash. Then write down what they tell you.
Georgia’s Minimum Insurance Rules and the Uninsured Driver Problem
Federal rules set minimum insurance for some trucks, and those rules can matter in a truck case. Under the federal schedule of limits for public liability in § 387.9, the minimum level of financial responsibility for for-hire carriage of nonhazardous property in interstate or foreign commerce, with a gross vehicle weight rating of 10,001 or more pounds, is $750,000. Under the federal motor carrier financial responsibility rules, no motor carrier may operate a motor vehicle until it has obtained and has in effect the minimum levels of financial responsibility set forth in § 387.9.
These numbers apply only when the rules cover the truck. Whether they do depends on the trip, the cargo and the type of carrier. That is a question to review on the facts, not an assumption.
A federal minimum is a floor, not a ceiling. A serious injury can cost more than the coverage available. So the amount of insurance and the value of an injury are separate questions.
Keep two questions apart. “What if I don’t have car insurance?” is about your own coverage. “Did the other driver have insurance?” is about theirs. Both matter, and each has its own paper trail.
Is It Worth Suing an Uninsured Motorist?
It can be worth reviewing, but the answer depends on who can pay. Collecting under your own UM coverage works differently from pursuing an individual driver or a trucking company directly.
Collectability depends on the at-fault party’s assets, employer and insurance. The value of a claim and the ability to pay it are different questions. A claim can be well documented and still be hard to collect.
Georgia uses modified comparative fault. Under O.C.G.A. § 51-12-33-pdf.pdf)-pdf.pdf)-pdf.pdf)-pdf.pdf), damages are reduced in proportion to your percentage of fault. If you are 50 percent or more responsible, you recover nothing. Each defendant pays only its own share.
Whether an insurance company can be named in a lawsuit depends on the specific facts of each case. Filing an insurance claim is different from suing the insurer.
Paying for Treatment: Payment Plans, Letters of Protection and Medical Factoring
You can ask a provider for a payment plan while a claim is pending, and you should ask in writing. Some providers treat injured patients under a letter of protection (LOP). Others sell the bill to a factoring company. Each option has terms you need to understand.
A letter of protection is a written promise to pay the provider from any recovery. Under O.C.G.A. § 51-12-1.1-pdf.pdf)-pdf.pdf)-pdf.pdf)-pdf.pdf), the letter itself, itemized charges and any referral are relevant and discoverable. Georgia also limits the collateral source rule so this evidence can come in.
Medical factoring means a company buys the right to a medical bill, usually at a discount, and then seeks payment from your recovery. Under the same statute, if a provider sells its receivables below invoice price, the buyer’s name and the price paid are discoverable. These terms can reduce what you keep.
Medical expenses are also limited to the reasonable value of medically necessary care. The trier of fact decides that amount under O.C.G.A. § 51-12-1.1-pdf.pdf)-pdf.pdf)-pdf.pdf)-pdf.pdf). A bill’s total is not automatically the amount recoverable.
Before you sign, ask what the arrangement costs and what it means for your share. Don’t sign anything about your claim you don’t understand.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Hospital Bills, Liens and Collection Calls
A collection call doesn’t mean the full bill is due that day. Ask the caller for the itemized bill and the amount due, in writing. Don’t rely on a phone conversation alone.
Ask every provider whether it claims any interest in a future recovery, and get the answer in writing. Keep copies of everything you send and receive.
Missed payments can lead to collection accounts that affect your credit. Keeping the provider informed in writing helps. Ask whether the account can be held while your claim is evaluated.
Don’t ignore letters from a collector. A short written reply keeps the record clear and gives you time to review your options.
Why Legal Help Matters in a No-Insurance Truck Case
A lawyer can review your own coverage, the at-fault party’s coverage and your medical payment options together. That matters because truck cases often involve more parties and more records than a typical car crash. A driver, a trucking company and one or more insurers may all be involved.
Early steps shape what evidence exists later. A lawyer can tell you which records to request now, before they are harder to get. Our truck accident lawyer page describes how the firm handles these cases.
Terance Madden has been in practice since 1999. The firm has offices in Jonesboro (Clayton County), Atlanta, Decatur, Macon and Augusta. Our team helps gather records and keeps you updated. Terance Madden is the responsible attorney for this page.
The firm works on a no-fee-unless-we-win basis, but you may still be responsible for court costs and case expenses.
Keeping Evidence While You Sort Out the Bills
Ask early for the truck’s records, because timing matters. Under the federal hours-of-service recordkeeping rules, a motor carrier subject to those requirements, other than a private motor carrier of passengers (nonbusiness), must require each driver it uses to record the driver’s duty status for each 24-hour period using the prescribed method, which generally means an electronic logging device (ELD), although in certain circumstances a carrier may require manual recording instead. Those logs can show driving hours before the crash.
After a truck crash on a public road, federal rules require the employer to test the surviving driver for alcohol only in specific cases. In a crash that does not involve a fatality, testing is required only if the driver receives a citation under State or local law for a moving traffic violation arising from the accident within 8 hours, and either someone receives immediate medical treatment away from the scene or a vehicle had disabling damage requiring it to be towed or transported away from the scene (49 C.F.R. § 382.303). Controlled-substance testing follows separate requirements under the same regulation. Under the federal post-accident testing rules, as soon as practicable following an occurrence involving a commercial motor vehicle operating on a public road in commerce, each employer must test for alcohol each surviving driver who was performing safety-sensitive functions with respect to the vehicle, if the accident involved the loss of human life.
Write down what you remember now, in your own words, with the date and time. The other driver’s account may change later. Save photos, videos, dashcam footage and the names of any witnesses.
Can I still make a claim without health insurance?
How long do I have to file a lawsuit in Georgia?
Georgia generally requires an injury lawsuit within two years after the right of action accrues, under O.C.G.A. § 9-3-33-2023-pdf.pdf)-2023-pdf.pdf)-2023-pdf.pdf)-2023-pdf.pdf). Some exceptions apply, so don’t wait.
Do I have to pay a lawyer up front to talk about my case?
No. The first consultation is free, confidential and comes with no obligation to continue.
If a truck crash left you with medical bills and no health insurance, you don’t have to sort it out alone. Our team can talk it through with you, starting with a free case evaluation.
How We Help With Medical Bills After a Truck Crash
Our team supports you
Our team, led by attorney Terance Madden, helps you organize records, track providers and understand the medical bills that come after a truck crash.
Clear, organized paperwork
We help you gather crash reports, treatment notes, bills and insurance correspondence so every option is laid out in one place.
Fees explained up front
We work on injury claims with no fees unless there is a recovery. You may still be responsible for court costs and case expenses, and we explain these before you decide anything.
Direct answers
Terance Madden will talk with you about your injuries, your coverage and the steps ahead in plain language, with no pressure.
Don't Wait to Get Care
Delaying treatment after a truck wreck can leave your injuries undocumented and make it harder to connect your care to the crash. Get medical attention first, then call us so we can review your bills and coverage together.
First Steps After a Truck Wreck Without Health Insurance
1. Get medical care now
Your health comes first. Get evaluated and follow the treatment plan your providers recommend, even if you are unsure how the bills will be paid.
2. Keep every record
Save bills, receipts, prescriptions, mileage to appointments and any letters from insurers. Complete records make your situation easier to explain.
3. Check your own auto policy
Review your auto insurance for medical payments or personal injury protection coverage. Ask your insurer what it covers before you pay any bill out of pocket.
4. Talk with us
Call T. Madden & Associates, P.C. for a free, confidential consultation. We will review your medical bills, coverage and the truck company's insurance with you.