

Car Accident Lawyer | Georgia
Is Uninsured Motorist Coverage Required in Georgia?
Plain answers about UM coverage from T. Madden & Associates, P.C., a Georgia personal injury firm serving clients since 1999. Your first consultation is free, confidential, and carries no obligation to continue.
Serving Georgia Since 1999
1999
Year the firm began practice
5
Georgia offices: Jonesboro, Atlanta, Decatur, Macon and Augusta
24/7
Call us anytime
By Terance Madden · Published October 28, 2026
Is uninsured motorist coverage required in Georgia?
Is uninsured motorist coverage required in GA?
It says a liability policy must contain provisions that pay the insured for bodily injury, loss of consortium, or death caused by the owner or operator of an uninsured vehicle. Loss of consortium means a spouse’s claim for the harm an injury does to the marriage.
Being offered coverage and being required to buy it are different things. The insurer has to include or offer the coverage. You decide whether to keep it, and rejecting it requires a written step. The exact form and limits depend on your policy and the choices you make.
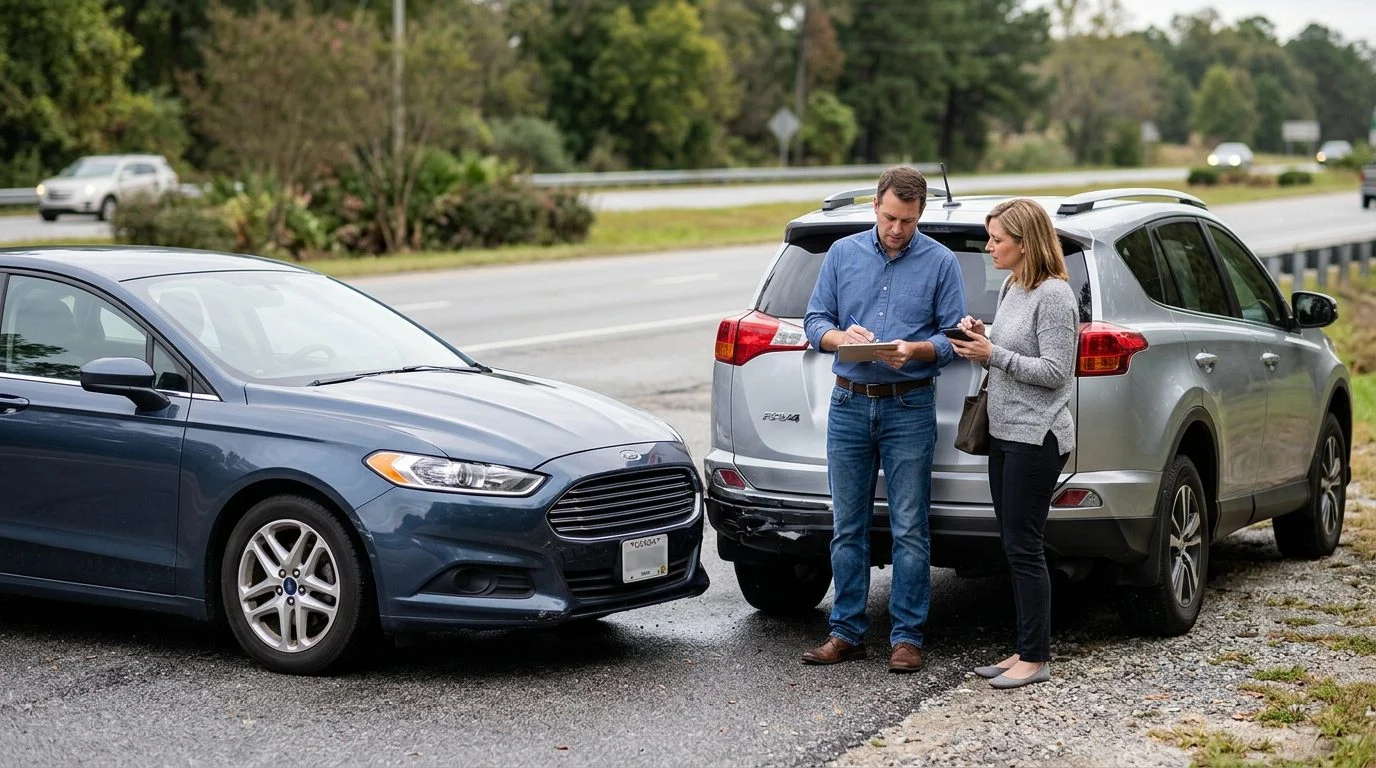
Many people ask this question for a relative who was hurt. It matters most when the other driver has no insurance at all, because your own policy may be the only source of payment.
If an uninsured driver hurt you or someone you love, you don't have to sort out the policy alone. Our team offers a free, confidential first consultation. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Georgia minimum liability requirements and why they matter
Those limits pay for injuries and property damage that a driver causes to other people.
Liability coverage does not pay your own injuries. It pays the other person when you are at fault. If you are hurt by someone else, your own uninsured or underinsured coverage is what matters.
Minimum limits can leave an injured person short. When the at-fault driver carries less coverage than the losses from the crash, the gap can be large. This is the main reason UM and UIM coverage exist. Medical bills, lost pay, and long recovery periods can add up fast after a serious wreck.
Limits also control how much you can recover from the at-fault driver’s policy. Check the declarations page of the policy to see your own limits.
What uninsured and underinsured motorist coverage pays for
Uninsured motorist (UM) coverage pays your injury losses when the at-fault driver has no insurance. Underinsured motorist (UIM) coverage applies when the at-fault driver’s liability limits are too low to cover your losses.
The Insurance Information Institute says these coverages may reimburse policyholders after accidents involving uninsured, underinsured, or hit-and-run drivers, as described in its facts and statistics on uninsured motorists. The Georgia Office of the Commissioner of Insurance states that UM coverage may protect against vehicle damage or injuries to the insured and passengers when an uninsured driver causes the accident.
Claims for injuries often include medical bills and lost income. These are the economic losses. Pain and suffering are noneconomic losses.
The coverage pays for losses you actually suffered, not for a windfall.
Add-on vs. reduced-by coverage: know what your policy says
Add-on UM pays in addition to the at-fault driver’s liability payment. Reduced-by coverage lowers your UM amount by the liability limits of the at-fault driver’s policy. The statute describes both structures.
Under the add-on structure, the at-fault driver’s liability payment does not reduce your UM limit. UM sits on top of it.
Under the reduced-by structure, you reject the full coverage in writing and choose a narrower option. The result is usually less protection than add-on.
Your declarations page and UM endorsement show which structure applies to your policy. Look at those documents before a crash, not after one.
Rejecting UM coverage: the written waiver
Rejecting UM coverage, or choosing a narrower option, must be done in writing. Keep the signed form with your policy papers.
Many drivers sign these forms during a busy sign-up and never look at them again. That is a common and costly mistake. A signed rejection can leave you without UM protection if the at-fault driver is uninsured.
Review your declarations page at each renewal to confirm your selections still match what you want.
A rejection does not change how the crash happened. It changes whether UM helps pay your losses when the other driver can’t.
Types of car insurance Georgia drivers commonly carry
Liability insurance pays other people for injury and property damage you cause.
Collision insurance pays to repair your own vehicle after a crash, subject to your deductible. Comprehensive insurance covers losses that don’t involve a collision, such as theft, fire, or weather damage.
Medical payments coverage, where your policy includes it, helps pay medical bills for you and your passengers after a crash. Its terms depend on the policy.
Uninsured and underinsured motorist coverage protects you when the at-fault driver lacks enough insurance. Your declarations page lists which coverages you carry. Our car accident lawyer page explains how these coverages fit into a claim after a crash.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What is not covered under uninsured motorist coverage?
UM coverage does not cover every loss. It applies to injuries from covered accidents involving uninsured or underinsured vehicles, and only within the policy’s terms.
Policies contain exclusions and conditions. Some exclusions involve intentional acts. Others involve vehicles that are not covered by the policy or people who do not qualify as covered persons. Conditions can include timely notice to the insurer.
The policy’s wording controls the result. Your policy defines who counts as a covered person and which vehicles count as covered vehicles. Those definitions decide whether UM applies to your situation.
Because exclusions vary, a claim can turn on details like where the person was riding or which vehicle was involved. Each situation depends on the facts.
What the main purpose of auto insurance is
Auto insurance spreads the financial risk of a crash. It helps injured people and property owners get paid when a driver causes harm.
Liability coverage pays others. UM and UIM coverage fill the gap when the at-fault driver cannot pay enough. Together, they help protect your own finances when another driver’s insurance falls short.
This protection only helps if the coverage is in place on the day of the accident. A policy that lapsed or never included UM will not respond after the crash.
Court deadlines are separate from insurance steps. Except as otherwise provided in this article, actions for injuries to the person must be brought within two years after the right of action accrues under O.C.G.A. § 9-3-33, with exceptions for injuries to the reputation, which must be brought within one year after the right of action accrues, and for actions for injuries to the person involving loss of consortium, which must be brought within four years after the right of action accrues.
Frequently asked questions about UM coverage in Georgia
Is uninsured motorist coverage required in GA?
Georgia law requires policies to include UM coverage unless the insured rejects it in writing. Insurers must offer it.
Can I be covered by UM as a passenger in someone else’s car?
Yes, the Georgia Office of the Commissioner of Insurance says UM may protect passengers. Who qualifies depends on your policy’s terms.
Does UM coverage apply to a hit-and-run driver?
Yes, the Insurance Information Institute says UM and UIM may reimburse policyholders after hit-and-run accidents. Your policy’s terms still control the result.
Should I contact my insurer after a crash with an uninsured driver?
Yes, report the crash to your insurer promptly. Your policy explains how and when to report a claim.
Talk with T. Madden & Associates about a crash involving an uninsured driver
If you are reading this after a crash, you may be waiting on hospital bills, answering your insurer’s questions, or helping an injured family member. That is a lot to carry at once.
Our team at T. Madden & Associates, P.C. offers a free, confidential first consultation, with no obligation to continue. You can reach us through our contact page to talk through your situation.
This page is general information, not legal advice. Responsible lawyer: Terance Madden, one of the lawyers at T. Madden & Associates, P.C., a Georgia personal injury firm practicing since 1999. Offices: Jonesboro (Clayton County), Atlanta, Decatur, Macon, and Augusta. Contact: https://www.tmaddenlaw.com/contact/.
Reviewing Your Coverage Before You Need It
Check your declarations page
Your policy's declarations page lists the coverages you carry, including any uninsured or underinsured motorist limits.
Ask how UM applies to passengers
Coverage for passengers can depend on the policy's terms, so ask about who is covered if you ride in someone else's vehicle.
Note any written rejection
If you ever declined or changed UM coverage, keep a copy of the signed form with your policy papers.
Save your accident records
Keep the crash report, photos, medical bills and insurance correspondence together so they are easy to share.
How We Can Help
Confidential first consultation
Discuss your insurance questions and your accident with our team at no charge and with no obligation to continue.
Focused on injured Georgians
We represent people hurt in car and truck wrecks, motorcycle and e-bike crashes, and other injury cases throughout Georgia.
Clear explanations of your options
We review your policy language and explain how UM coverage may apply to your situation in plain terms.
Fees only if there is a recovery
No fee is owed unless there is a recovery. Clients may still be responsible for court costs and case expenses, which we will explain up front.
Don't Wait to Look at Your Policy
Many drivers never read their UM and UIM coverage language until after a crash. Reviewing your policy now can help you understand your protection before you need it.