

Georgia Injury Claims | Clayton County, Atlanta, Decatur, Macon and Augusta
When Someone Else Caused the Crash, How Does Insurance Work?
A plain-language guide from T. Madden & Associates, P.C., a Georgia personal injury firm in practice since 1999, to the insurance coverage that may apply when you were hurt and were not at fault.
About Our Firm
1999
Year the firm began practice
5
Georgia offices
24/7
Phone line for case calls
By Terance Madden · Published November 3, 2026
The short answer: in Georgia, fault decides which insurance pays
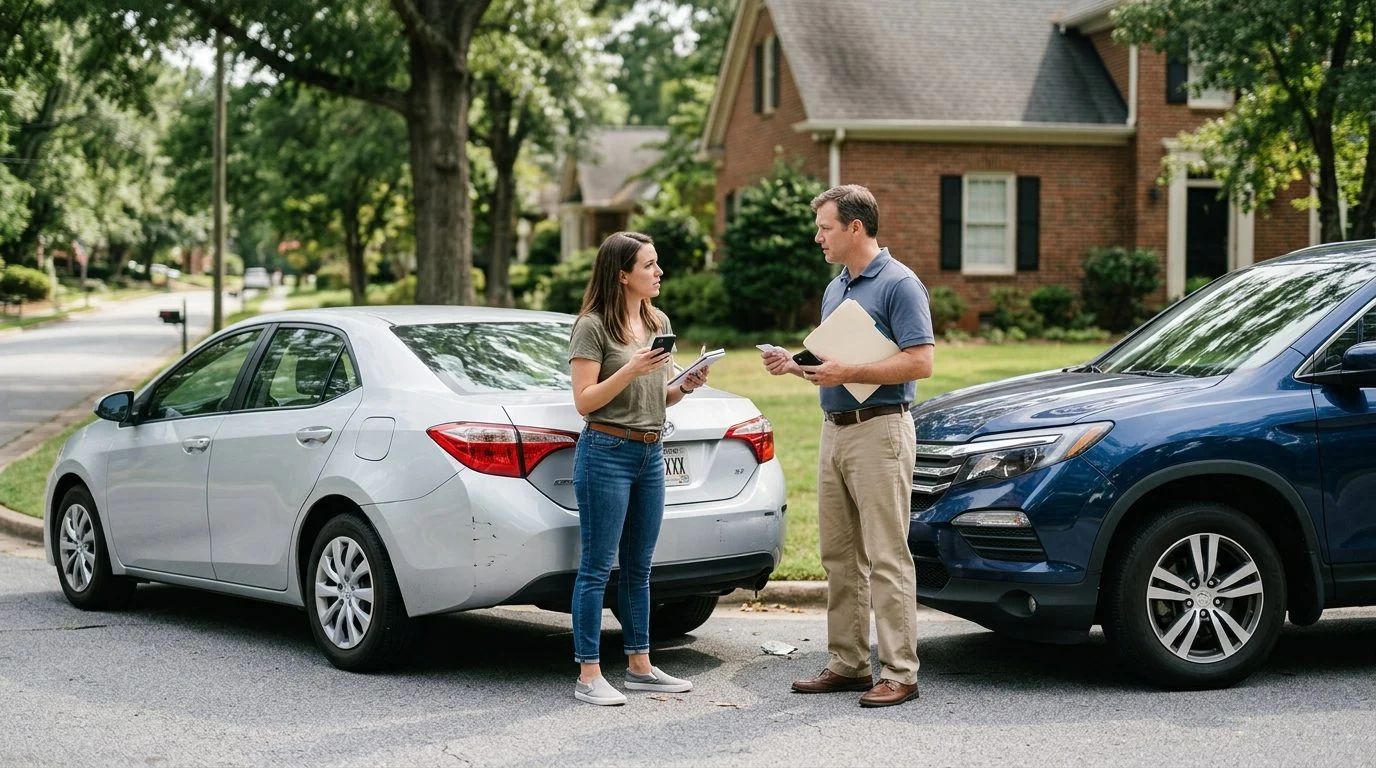
When another driver causes your crash, the claim for your injuries and vehicle damage usually goes to that driver’s liability insurance. Your own policy can still matter, especially for uninsured motorist, collision and medical payments coverage. So how does insurance work if it’s not your fault? Fault drives the answer. It decides whose insurance pays first and how much you can recover.
Insurers don’t decide this by who calls first. The key questions are who caused the crash, how much each person contributed, and what coverage exists on each side. This matters most in the first days after a crash, when calls and paperwork start coming in fast. The facts of your crash decide how these rules apply to you.
Waiting on an adjuster after a crash you didn't cause is stressful, and you don't have to sort it out alone. Reach out to T. Madden & Associates for a free, confidential first consultation. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Georgia is an at-fault state, not a no-fault state
A person hurt by someone else’s negligence generally pursues that person’s insurer. Georgia’s general injury-claim rules are built on fault, not on a set payment from your own policy.
Many searches on this topic mention “no-fault insurance.” In a no-fault system, your own policy pays a set amount of personal injury protection after a crash, whatever caused it. That is a different system from the one that governs most Georgia injury claims. Under O.C.G.A. § 51-1-6, an injured person may recover for a breach of a legal duty that causes damage.
Fault is judged by a standard of care. Under O.C.G.A. § 51-1-2, ordinary diligence is the care an ordinarily prudent person takes in similar circumstances. Failing to use that care is ordinary negligence. In your claim, the question is whether the other driver fell short of that standard and caused your harm.
How the claim works when another driver is at fault
The at-fault driver’s liability insurance is usually the main source of payment for your damages, up to its policy limits. Liability coverage pays for injury and property damage the policyholder causes to others. The adjuster on that claim works for the at-fault driver’s insurer, not for you. Their goal is to resolve the claim for that insurer, so an early offer may not reflect your full losses.
Your own policy can add protection. Under the Georgia uninsured motorist statute, automobile liability policies issued or delivered in Georgia for a motor vehicle principally garaged or principally used in Georgia must include uninsured motorist coverage with limits the policyholder can choose, unless a named insured rejects that coverage in writing (O.C.G.A. § 33-7-11). O.C.G.A. § 33-7-11 reads: “(a)(1) No automobile liability policy or motor vehicle liability policy shall be issued or delivered in this state to the owner of such vehicle or shall be issued or delivered by any insurer licensed in this state upon any motor vehicle then principally garaged or principally used in this state unless it contains an endorsement or provisions undertaking to pay the insured damages for bodily injury, loss of consortium or death of an insured, or for injury to or destruction of property of an insured under the named insured’s policy sustained from the owner or operator of an uninsured motor vehicle, within limits exclusive of interests and costs which at the option of the insured shall be.” Under O.C.G.A. § 33-7-11, that coverage can apply when the at-fault driver has no bodily injury liability insurance, or when the at-fault driver’s bodily injury liability insurance is in existence but the insurance company writing the insurance has legally denied coverage under its policy. O.C.G.A. § 33-7-11 reads: “(iv) Bodily injury liability and property damage liability insurance in existence but the insurance company writing the insurance is unable, because of being insolvent, to make either full or partial payment with respect to the legal liability of its insured, provided that in the event that a partial payment is made by or on behalf of the insolvent insurer with respect to the legal liability of its insured, then the motor vehicle shall only be considered to be uninsured for the amount of the difference between the partial payment and the limits of the uninsured motorist coverage provided under the insured’s motor vehicle insurance policy; or.” Before the vehicle can be treated as uninsured because the at-fault driver’s insurer is insolvent, you must notify your own uninsured motorist insurer, within a reasonable time, of any legal proceeding against the insolvent company that you know about. You must give this notice before you enter into any negotiation or arrangement with that company and before your insurer is prejudiced by anything you do or fail to do about the insolvency. Medical payments coverage can help with medical bills, depending on what you carried.
Two kinds of damages matter here. General damages, such as pain and suffering, are those the law presumes flow from a wrongful act. They can be recovered without proof of an amount. Special damages, such as medical bills and lost pay, must be proved (O.C.G.A. § 51-12-2). Keep bills, pay records and treatment notes from the start.
What changes when a truck or commercial vehicle is involved
When a commercial truck is involved, more parties and more insurance usually come into play. Federal rules set minimum liability levels for many for-hire carriers. For-hire interstate or foreign carriage of nonhazardous property in trucks rated 10,001 pounds or more, the minimum is $750,000 (49 C.F.R. § 387.9).
Georgia law also makes an employer liable for certain employee torts. Under O.C.G.A. § 51-2-2, a person is liable for torts committed by a servant by his command or in the prosecution and within the scope of his business. That is why a driver’s employer may be part of a truck claim. Asking for the carrier’s certificate of insurance is a useful early step.
Joining the carrier’s insurer to a lawsuit has limits. Under O.C.G.A. § 40-1-112(c), the insurer can be joined in the same action only in narrow cases. Examples include when one or more related motor carriers is insolvent or bankrupt, or when personal service, as provided in subsection (e) of Code Section 9-11-4, cannot after reasonable diligence be effected. This is one reason truck claims can be more complex than a passenger-car crash.
What the at-fault driver’s insurance may not cover
The at-fault driver’s policy pays only up to its limits. If your losses are larger than those limits, that policy may not pay the full amount. If the at-fault driver has no insurance, your own uninsured motorist coverage may be the path to payment.
Some losses fall outside a policy. Policies carry exclusions for certain intentional acts and certain vehicle uses, so read the exclusions in the policy itself. A common mistake is treating an early check as the final answer. Before you accept money, make sure your medical picture is clear.
Medical bills get special treatment. Under O.C.G.A. § 51-12-1.1(b), medical expense damages are limited to the reasonable value of medically necessary care. If you have health insurance, the evidence can include both the amounts charged and the amounts actually needed to satisfy them under your insurance contract (§ 51-12-1.1(c)).
Property damage, medical bills, lost wages and pain and suffering are different categories. An early offer may not address every category, so compare it against all your losses.
Talking to adjusters and reporting the crash
Stick to the facts, and don’t guess about fault or injuries. The Georgia Office of the Commissioner of Insurance and Safety Fire recommends promptly notifying police and the insurer, collecting accident and witness information, documenting the scene, and avoiding statements about fault (Georgia auto claim tips).
Don’t rush to accept an offer. The state’s guidance says claimants may negotiate with the insurer for a fair settlement (Georgia insurance claim tips). Before you give a recorded statement or sign a release, make sure you know how serious your injuries are. Keep copies of everything you send and receive, including emails, letters and photos.
Report the crash to your own insurer too, even when you weren’t at fault. Your policy sets its own notice terms, so reading them is a sensible step.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Deadlines, comparative fault, and talking with our lawyers
Georgia generally allows two years to file a personal injury lawsuit under O.C.G.A. § 9-3-33. Fault can also reduce what you recover. Under O.C.G.A. § 51-12-33, the judge reduces an award in proportion to the plaintiff’s percentage of fault. A plaintiff who is 50 percent or more responsible for the injury or damages claimed receives no damages. Each at-fault party also pays only its own share, not a joint share.
How does insurance work if it’s not your fault?
Usually, the at-fault driver’s liability insurance pays first, up to its policy limits. Your own uninsured motorist, collision or medical payments coverage may add protection, depending on what you carried.
Can I still recover if I was partly at fault?
Yes, if you are less than 50 percent responsible. Under O.C.G.A. § 51-12-33, where the plaintiff is to some degree responsible for the injury or damages claimed, the trier of fact determines the plaintiff’s percentage of fault, and the judge reduces the damages otherwise awarded to the plaintiff in proportion to that percentage. Under subsection (g), the plaintiff is not entitled to receive any damages if the plaintiff is 50 percent or more responsible for the injury or damages claimed.
How long do I have to sue in Georgia?
Georgia generally allows two years to file a personal injury lawsuit (O.C.G.A. § 9-3-33; Kenneth B. Cameron v. Jmp Pizza, Inc (2026)).
If you’re waiting on an adjuster after a crash you didn’t cause, you don’t have to sort it out alone. Reach out to our lawyers for a free, confidential first consultation, with no obligation to continue.
This page is general information, not legal advice. Terance Madden is the responsible lawyer for this page. T. Madden & Associates, P.C. has been in practice since 1999, with offices in Jonesboro (Clayton County), Atlanta, Decatur, Macon and Augusta. Contact details are at tmaddenlaw.com/contact.
Coverage That May Be Involved
At-Fault Driver's Liability Insurance
This is the policy of the person who caused the crash. It is often the first source of payment for injury claims, up to the policy limits.
Your Uninsured or Underinsured Motorist Coverage
If the at-fault driver has no insurance or too little coverage, this part of your own policy may add protection, depending on what you carried.
Your Collision and Medical Payments Coverage
Your own policy may help with vehicle damage or medical bills while a claim is pending, depending on the coverage in place at the time of the crash.
Other Available Sources
Depending on the facts, other policies or parties may be relevant. A lawyer can review the policies involved and explain which ones may apply to your situation.
How Our Firm Helps Injury Clients
We Review the Policies
We look at the at-fault driver's coverage and your own policy to identify the insurance that may apply to your injuries.
We Deal With the Insurers
Insurance companies often contact injured people quickly. Our team handles communications with adjusters so you can focus on recovering.
We Explain Each Step
We answer your questions in clear terms, from the first call through any settlement discussions or court proceedings.
Fees and Costs Are Explained Upfront
We handle injury cases on a no-fee basis, meaning no fees unless there is a recovery. You may still be responsible for court costs and case expenses, which we will explain before you decide.
Speak With a Lawyer Before You Sign Anything
Adjusters may ask for a recorded statement or offer a quick settlement. Talk with a lawyer before you give statements or accept any offer, so you understand what the policy covers and what you may be giving up.