

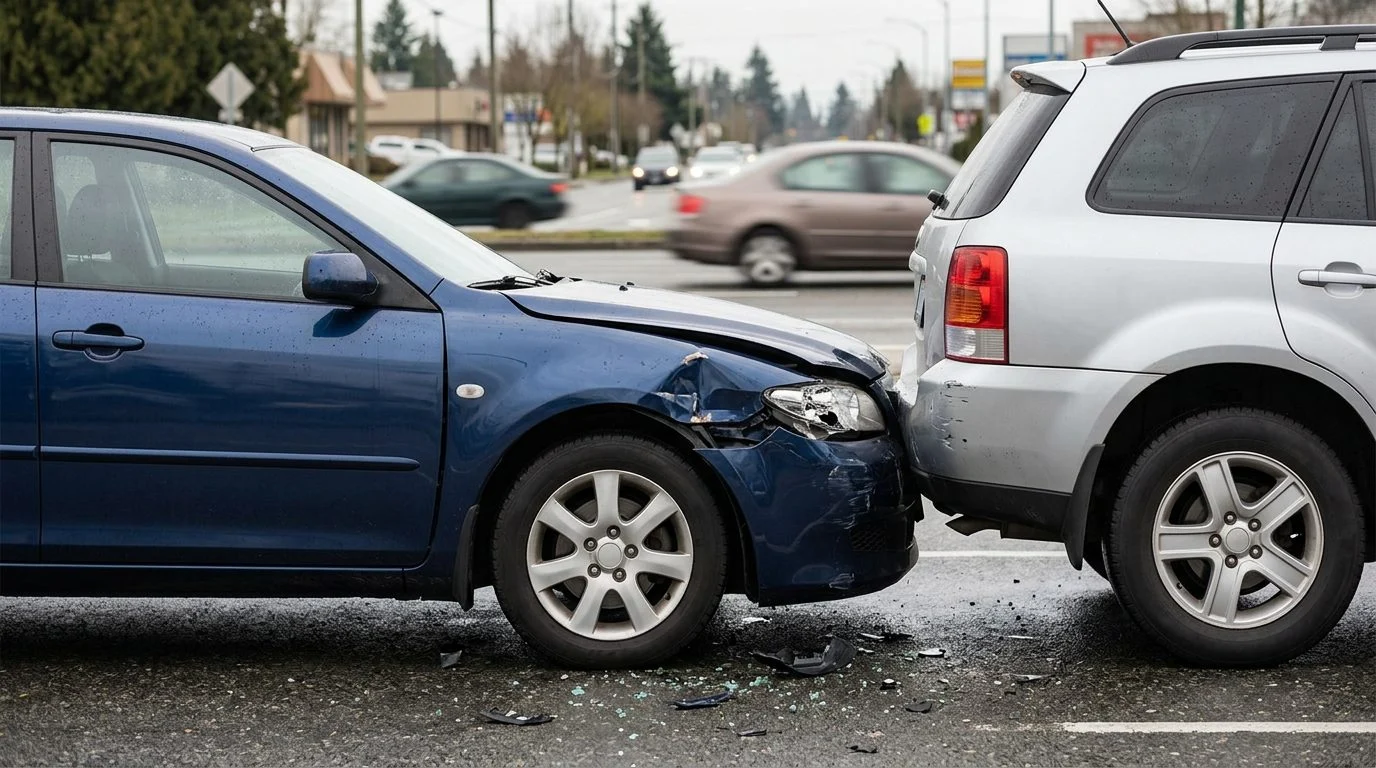
Car, Truck & Motorcycle Accidents | Georgia
When Bodily Injury Coverage Isn't Enough, Your Options Still Matter
T. Madden & Associates, P.C. has represented injured Georgians since 1999. We help clients look beyond the at-fault driver's policy limits and review every source of coverage.
Serving Georgia Since 1999
1999
Year the firm began practice
5
Offices across Georgia
Free
First consultation, confidential and without obligation
By Terance Madden · Published October 28, 2026
If you’re asking what happens if you don’t have enough bodily injury coverage, here’s the short answer. The gap between your losses and the insurance available can fall on the at-fault driver personally. Your own uninsured or underinsured motorist coverage may also help.
This page explains how Georgia’s bodily injury limits work, where that gap comes from, and which other sources you should understand. Medical bills can arrive fast after a crash, and the other driver’s policy may be smaller than you expect. Knowing the rules early helps you ask better questions.
What bodily injury liability coverage pays for
Bodily injury (BI) liability coverage pays other people’s injury losses when the policyholder is found at fault in a crash. It pays for the injured person’s medical bills and other losses caused by the injury.
It does not pay for damage to the other person’s vehicle. That falls under property damage (PD) coverage, which is a separate part of the same policy.
Here is the key point. BI limits are a cap on what the insurer pays. They are not a measure of what the injured person has lost. If the losses are larger than the cap, the difference is a gap.
If medical bills are piling up and the other driver's policy may not be enough, our team is ready to talk through your options with you. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
How liability limits work in Georgia: per person and per accident
That means $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage, according to the Insurance Information Institute.
The per-person limit is the most the insurer pays for any one injured person. The per-accident limit is the most it pays for everyone hurt in the same crash, combined.
Say a crash injures three people, and the at-fault driver carries 25/50/25. The first person has $40,000 in medical bills. The policy pays that person $25,000, which reaches the per-person limit. The other two people share the remaining $25,000 of the per-accident limit. If each has $30,000 in losses, they split that money, and neither gets full value for their losses.
A minimum policy can run out fast. Hospital stays, surgery, and a long recovery can add up to far more than $25,000 for one person.
What happens when the at-fault driver’s coverage is too low
When the at-fault driver’s bodily injury limit is used up, the insurer generally stops paying injury claims at that limit. The injured person then faces a gap between total losses and the money left on that policy.
A California Department of Insurance consumer brochure states the general principle. Losses from a crash can exceed the auto liability limits on a policy, so it is worth reviewing those limits as soon as possible after an accident. That brochure covers California, but it shows how a policy cap can leave a gap.
A judgment is also not the same as payment. An injured person may win a judgment against the at-fault driver. Collecting it depends on what that driver owns and earns. Personal assets and wages can become part of that discussion, depending on the facts.
Does uninsured or underinsured motorist coverage pay for pain and suffering?
Uninsured motorist (UM) and underinsured motorist (UIM) coverage is part of your own auto policy. It can apply when the at-fault driver has no insurance or not enough insurance.
Under O.C.G.A. § 33-7-11, an auto policy in Georgia must include an endorsement that pays the insured for bodily injury from an uninsured vehicle’s owner or operator. O.C.G.A. § 33-7-11 reads: “(a)(1) No automobile liability policy or motor vehicle liability policy shall be issued or delivered in this state to the owner of such vehicle or shall be issued or delivered by any insurer licensed in this state upon any motor vehicle then principally garaged or principally used in this state unless it contains an endorsement or provisions undertaking to pay the insured damages for bodily injury, loss of consortium or death of an insured, or for injury to or destruction of property of an insured under the named insured’s policy sustained from the owner or operator of an uninsured motor vehicle, within limits exclusive of interests and costs which at the option of the insured shall be.” Georgia law also allows the policy provisions that provide this uninsured motorist coverage to exclude the insurer’s liability for bodily injury or death for which the insured has already been compensated through medical payments coverage or under workers’ compensation laws, and for property damage the insured has already been compensated for by other property or physical damage insurance (O.C.G.A. § 33-7-11(i)). The combined recovery also cannot exceed the sum of all economic and noneconomic losses.
Injury claims can include general damages. They can be recovered without proof of a set amount, under O.C.G.A. § 51-12-2.
Whether a UM or UIM claim pays for pain and suffering is governed by your policy’s wording and Georgia law. Read your policy, and ask about this point directly. If you have a UM claim, you typically notify your own insurer, document your losses, and wait for the insurer’s evaluation.
What happens if the other driver has no liability insurance
If the at-fault driver has no liability insurance, there is usually no insurer to pay the bodily injury claim. A driver without a policy has no insurer to pay the claim, but the insured’s own uninsured motorist coverage may pay damages for bodily injury, loss of consortium or death of an insured sustained from the owner or operator of an uninsured motor vehicle.
Under O.C.G.A. § 33-7-11, a vehicle is treated as uninsured in several cases, including when its bodily injury liability insurer has legally denied coverage under its policy. O.C.G.A. § 33-7-11 reads: “(iv) Bodily injury liability and property damage liability insurance in existence but the insurance company writing the insurance is unable, because of being insolvent, to make either full or partial payment with respect to the legal liability of its insured, provided that in the event that a partial payment is made by or on behalf of the insolvent insurer with respect to the legal liability of its insured, then the motor vehicle shall only be considered to be uninsured for the amount of the difference between the partial payment and the limits of the uninsured motorist coverage provided under the insured’s motor vehicle insurance policy; or.” Your own UM coverage may then be the main source of payment.
Without UM coverage, recovery may depend on the other driver’s personal assets. Check your declarations page. It lists your limits and shows whether you carry UM coverage. The statute also lets any insured named in the policy reject the required coverage in writing, so review what you signed. The coverage required under paragraph (1) of subsection (a) excludes umbrella or excess liability policies unless such policies or a policy endorsement affirmatively provide for it (O.C.G.A. § 33-7-11).
Options when medical bills exceed the liability limits
Medical bills can exceed liability limits. Several sources may help cover them, depending on what you carry.
- Your own health insurance
- Medical payments coverage, if your policy includes it
- Your UM or UIM coverage
- The at-fault driver’s personal assets
Health insurance and other payers may have reimbursement rules. Ask how those rules could affect what you keep from any settlement.
Georgia limits medical and healthcare damages to the reasonable value of medically necessary care, treatment, or services. See O.C.G.A. § 51-12-1.1. If you have health insurance, the evidence includes both the amounts charged and the amounts actually necessary to satisfy those charges under your insurance contract.
If a provider treats you under a letter of protection, that letter and the itemized charges are relevant and discoverable under the same statute. Gather bills, receipts, and records early. They form the basis of any injury claim.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Time limits that can affect your claim
Georgia generally gives two years to file a lawsuit for injuries to the person. O.C.G.A. § 9-3-33 sets that two-year period, which runs from when the right of action accrues, meaning when the claim begins. Claims for loss of consortium have four years under the same statute.
Missing the deadline can end your right to sue, even when coverage is still unclear. Don’t let the calendar slip while you sort out the insurance questions.
Early steps help protect your options. Report the crash, keep your records, and write down what happened while you still remember it.
How a personal injury lawyer fits in when coverage is not enough
A personal injury lawyer can review a limits problem from several sides at once. That usually means reading the at-fault driver’s policy and declarations page, finding your own UM or UIM coverage, and weighing possible claims against the other driver’s personal assets.
T. Madden & Associates, P.C. is a Georgia personal injury firm in practice since 1999. The firm handles car and truck accident claims, motorcycle and e-bike crashes, and other injury matters. It has offices in Jonesboro, Atlanta, Decatur, Macon, and Augusta.
Terance Madden is the responsible lawyer for this page. Shenia Madden is also one of the firm’s lawyers. Our lawyers do not promise any result. Each claim turns on its own facts and coverage.
Frequently asked questions
What happens if you don’t have enough bodily injury coverage?
The gap between your losses and the policy limit can fall on the at-fault driver personally. Your own UM or UIM coverage may also help.
How do the coverage limits on a policy affect a crash claim?
The coverage on a specific policy is worth reviewing after a crash, and our team can help you understand what applies to your case.
Does uninsured motorist coverage pay for pain and suffering?
Whether it does is governed by your policy’s wording and Georgia law. Ask your insurer and review your policy.
Georgia generally gives two years after the right of action accrues for actions for injuries to the person under O.C.G.A. § 9-3-33; injuries to the reputation must be brought within one year after the right of action accrues, and actions for injuries to the person involving loss of consortium within four years after the right of action accrues.
Talk with our team about your coverage and your options
If you’re reading this after a crash, you may be handling medical bills, calls from insurers, and an unclear picture of the other driver’s coverage. You may also be helping a family member through it. Our team can talk through your coverage and your options with you. Request a free case evaluation to start that conversation.
Our free first consultation is confidential and carries no obligation to continue. We handle injury cases on a no-fee-unless-we-win basis, but you may still be responsible for court costs and case expenses.
Terance Madden is the responsible lawyer for this page. Our offices are in Jonesboro, Atlanta, Decatur, Macon, and Augusta. You can call us 24/7.
Where the Rest of Your Losses May Come From
Your own UM or UIM coverage
Uninsured and underinsured motorist coverage on your own policy may help when the at-fault driver's bodily injury limits fall short. Its terms should be reviewed closely.
Every policy involved
Coverage limits and terms can differ from one policy to another. Reviewing each policy connected to the crash is a practical first step.
The at-fault driver personally
When losses exceed the policy limit, the remaining gap can fall on the at-fault driver personally. That is one reason the full picture matters.
Careful review by our team
Our lawyers and staff can help you understand how the policies involved may fit together after a crash.
No Fee Unless There Is a Recovery
Our fees are contingent: there is no fee unless there is a recovery. You may still be responsible for court costs and case expenses, so please ask us to explain how these are handled before you decide.
Questions to Ask After a Crash
Who was involved?
Identifying every driver and vehicle is an important starting point for understanding coverage.
What are the policy limits?
Knowing the bodily injury limits on each policy helps show whether a gap may exist.
What do my own policies cover?
Reviewing your own UM or UIM coverage and any other policies can reveal additional options.
How serious are my losses?
Medical bills, lost income and long-term needs help measure the full impact of the injury.