

Georgia Car Accident Lawyer | Clayton County and statewide
Hurt in a Georgia car crash? Get clear answers before you talk to an insurer.
Georgia's fault rules decide how an injury claim moves forward, and the first steps you take can shape what happens next. Talk with T. Madden & Associates, P.C. about your crash at no cost.
Serving injured Georgians since 1999
1999
Year the firm began practicing
5
Offices across Georgia
24/7
Phone line for crash victims
By Terance Madden · Published November 12, 2026
If a crash has left someone you love hurt, one question comes first: whose insurance pays? Does Georgia have a no-fault law for car accidents? No. Georgia is a fault state.
In a fault state, the driver who caused the crash is responsible for the harm. That driver’s liability insurance is the main source of money for the injured person. Here is what that means for your family.
The Short Answer: Georgia Does Not Have a No-Fault System
Georgia does not use a no-fault system for most injury claims, so an injured person can bring a claim against the at-fault driver. No-fault insurance means your own policy pays your medical bills first, no matter who caused the crash, and your right to sue the other driver is limited.
Georgia’s rules focus on who was responsible. Lawyers call that responsibility liability, meaning legal duty for harm caused by a careless choice behind the wheel.
Timing matters. O.C.G.A. § 9-3-33 says actions for injuries to the person must be brought within two years after the right of action accrues, except actions for injuries to the person involving loss of consortium, which must be brought within four years after the right of action accrues. Don’t let that clock run while the bills pile up.
If someone you love was hurt in a crash that wasn't their fault, our team can review which coverage applies, and the first consultation is free. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Fault vs. No-Fault, in Plain Words
In a fault system, the driver who caused the harm pays for it. In a no-fault system, your own policy pays first.
Picture a rear-end crash on a busy road in Clayton County. The other driver was following too close and hit your car at a stop light. Under Georgia’s fault rules, you bring the claim against that driver and their liability coverage. Under a no-fault system, your own policy would pay your medical bills first, and your right to sue would be narrower.
Your real decision is where to look first for money: your own policy, the other driver’s policy, or both. The answer depends on what coverage each person carries. Pull every policy that could apply before you decide anything.
How Georgia Decides Who Was at Fault
Georgia splits fault by percentage. An injured person who is 50 percent or more responsible cannot recover damages (O.C.G.A. § 51-12-33(g)).
Negligence means failing to use the care an ordinarily prudent person would use in the same situation. Speeding, texting, running a red light and following too closely are common examples. O.C.G.A. § 51-1-2 defines that failure as ordinary negligence.
Georgia uses modified comparative negligence (shared fault). Under O.C.G.A. § 51-12-33, a judge reduces the damages in proportion to the injured person’s share of fault. Under O.C.G.A. § 51-12-33, if you are partly responsible for your injury, the judge reduces your damages in proportion to your percentage of fault, and you cannot receive any damages if you are 50 percent or more responsible. Expect the other side to argue you added to the crash.
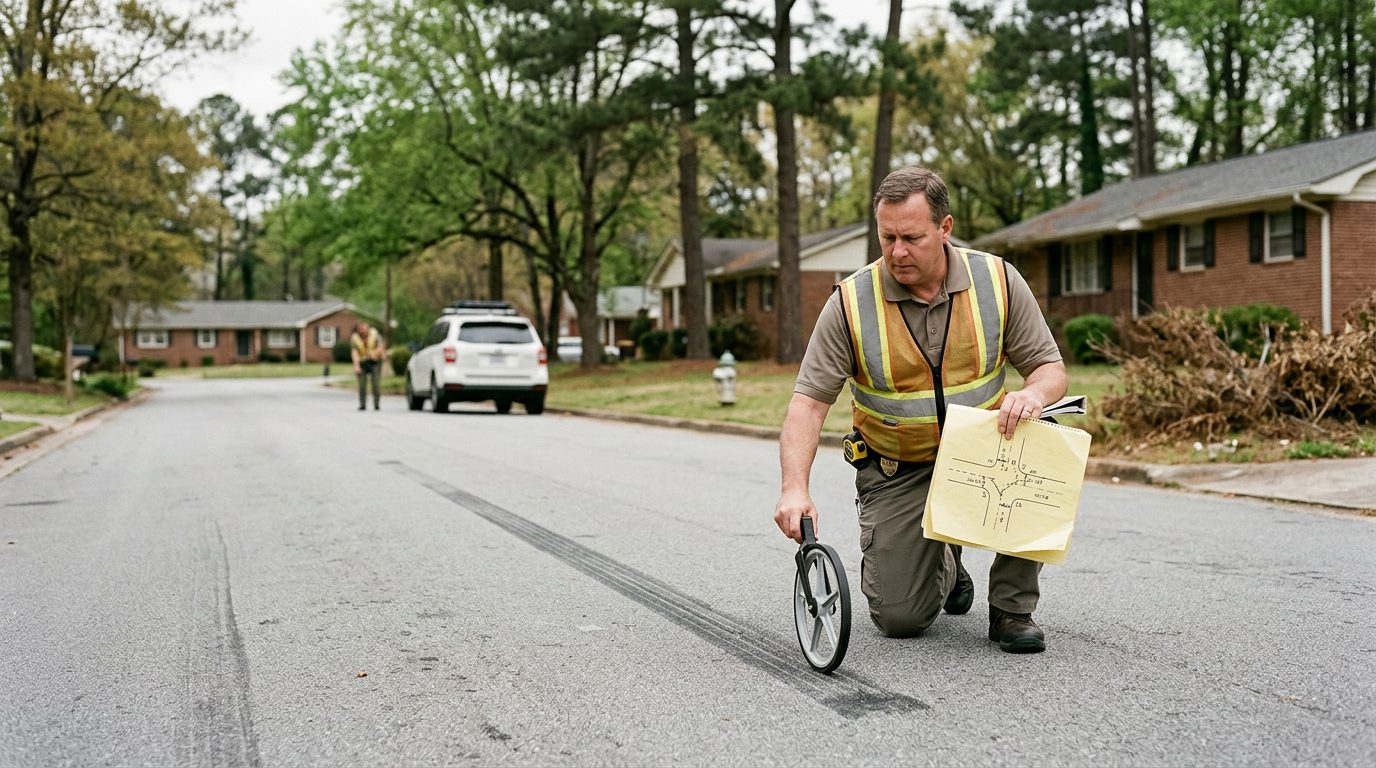
Crash evidence includes photos, skid marks, witness statements, the police report and vehicle data.
Before law school, Terance Madden trained as an electrical engineer. So he starts a case by asking what the evidence shows and how the crash happened. Many vehicles record speed and braking data near the moment of impact, and that data can be lost if no one asks for it early. He works to find which records exist and to make sure they are kept.
The Insurance Layers Behind an Injury Claim
The at-fault driver’s liability coverage is the first layer. It may not be enough for a serious injury. Under O.C.G.A. § 33-7-11, a Georgia auto liability policy must include uninsured motorist (UM) provisions. These pay the insured for injury caused by an uninsured owner or driver. The state’s Georgia auto insurance coverage guidance explains how that protection works.
Underinsured motorist (UIM) coverage applies when the at-fault driver has insurance, but not enough to cover the losses. Medical payments (MedPay) coverage, when your policy includes it, pays medical bills no matter who caused the crash.
Big Insurance is not on your side. Its adjusters often open with a low offer. They ask for a recorded statement before you understand the injuries, let the file sit while records are requested, and call a crash “low impact” so the injuries look minor. An insurer’s first offer is rarely what a claim is worth.
The response is to pursue every layer: the at-fault driver’s liability policy, UM and UIM, MedPay, any umbrella or excess policy, and corporate coverage when a company vehicle or commercial policy is involved. The firm looks at lifetime costs when injuries are long-term.
Can You Sue for Emotional Distress and Pain in Georgia?
Georgia law allows claims for losses beyond the bills, but the proof has to match the loss. Under O.C.G.A. § 51-12-2, general damages are presumed to flow from a wrongful act and can be recovered without proof of a set amount. Special damages actually flow from the act and must be proved.
Medical costs are special damages. O.C.G.A. § 51-12-1.1 limits them to the reasonable value of medically necessary care.
When the entire injury is to a person’s peace, happiness or feelings, O.C.G.A. § 51-12-6 says no measure of damages can be set except the “enlightened consciences of impartial jurors.” That makes daily-life evidence important. Keep a family member’s notes on sleep, mood, missed events and tasks your loved one can no longer do. Write them down with dates.
What Happens When Losses Exceed Coverage, and Is There a Minimum Settlement?
When losses are bigger than the coverage behind them, the gap is a serious problem for everyone involved. That is why every layer matters.
Georgia assigns each at-fault party its own share. Under O.C.G.A. § 51-12-33, each person’s apportioned share is that person’s own liability, not joint liability.
No formula sets a minimum settlement for a Georgia car crash. The value depends on the facts: the injuries, the medical bills, the lost income, the coverage available and how the injuries change daily life. Some readers also ask whether an at-fault driver can lose a home. That turns on the judgment, the coverage and that driver’s own assets.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
What the Person Managing the Claim Needs to Do Next
Start your records on day one. If you’re the spouse, mother or adult daughter answering the calls and sorting the bills, you’re carrying the hardest part of this claim. Keep these items together:
- The police report number and the names of any witnesses
- Photos of the vehicles, the road and any injuries, taken as soon as it’s safe
- Medical records, bills and appointment notes
- Pay stubs and a list of missed work
- A daily log of symptoms, sleep, mood and what your loved one can’t do
The Georgia Office of the Commissioner of Insurance and Safety Fire advises promptly notifying police and the insurer. It also advises collecting crash and witness information, documenting the scene, and avoiding statements about fault (Georgia auto claim tips).
Don’t give a recorded statement to Big Insurance until you understand the injuries and the coverage. You can say you’ll talk once the family has the facts.
Frequently Asked Questions
Is Georgia a no-fault state for car crashes?
No. Georgia is a fault state, so the at-fault driver’s liability coverage is the main source of payment for an injured person’s losses.
How long do I have to file a claim?
Under O.C.G.A. § 9-3-33, most injury actions must be brought within two years after the right of action accrues.
Can I recover if I was partly at fault?
Yes, if you are less than 50 percent responsible. Under Georgia law, if you are partly at fault, the judge reduces your damages in proportion to your percentage of fault (O.C.G.A. § 51-12-33(a)).
Who pays my medical bills after a crash?
The at-fault driver’s liability coverage is the main source for damages. MedPay may help with bills if your policy includes it.
Can I sue for emotional distress?
Emotional harm can be part of a claim. When the whole injury is emotional, jurors set the measure of damages.
Talk With the Firm About Your Family’s Situation
A crash wasn’t your choice. Now you’re trying to understand Georgia’s fault rules while calls and bills keep coming. If the crash left someone you love with medical bills, missed work or long-term limits on daily life, the firm can review which coverage applies.
T. Madden & Associates, P.C. has practiced since 1999 and has offices in Jonesboro, Atlanta, Decatur, Macon and Augusta. The firm is led by Terance Madden, the responsible lawyer for this page. Shenia Madden is also one of its lawyers. The first consultation is free, confidential and carries no obligation to continue.
When you’re ready, start your free case evaluation and bring the policy numbers and records you’ve gathered.